
When a European Group Closes a US Automotive Plant: The Board Decisions That Cannot Be Delegated
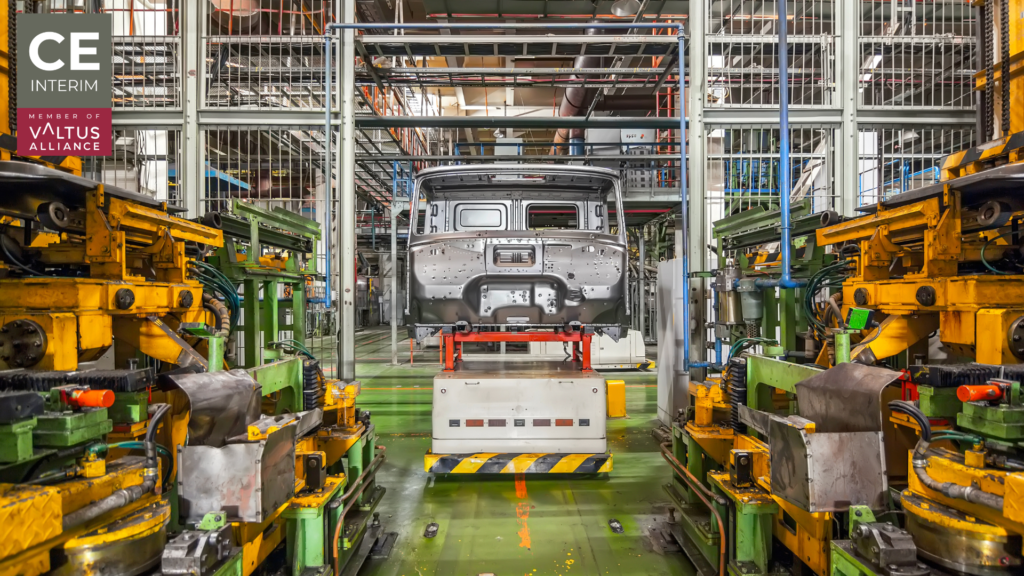
A European Group Board approves a US automotive plant closure and authorizes local execution. Soon, headquarters receives decisions that can alter the exit. An OEM asks for continued supply, a supplier seeks a settlement, or an environmental obligation survives production. The Board must decide which matters remain reserved and which belong with the US closure executive. The legal timetable starts before many of those decisions reach headquarters. The U.S. Department of Labor says the federal Worker Adjustment and Retraining Notification Act (WARN Act) generally applies to employers with 100 or more employees. It generally requires at least 60 calendar days of advance written notice for qualifying plant closings or mass layoffs. Under 20 CFR Part 639, a covered plant closing generally involves at least 50 employment losses at one site. The Board must define what a US automotive plant closure means before authority moves locally Closure scope needs a defined end condition Stopping production covers only one part of the exit. The Board should define the end condition before execution starts. That definition can cover employee separation, tooling transfer, equipment sale, property exit, environmental work, benefit actions, and legal entity treatment. An automotive plant shutdown USA program can finish production while other obligations continue. Workforce sequencing can move the legal timetable The DOL WARN Advisor says a WARN plant closing can arise when at least 50 employees lose employment at a site, facility, or operating unit during 30 days. The threshold excludes part-time employees. For a mass layoff involving 50 to 499 employees, the affected group generally must equal at least 33% of the active site workforce. At 500 or more employees, the 33% threshold does not apply. Those thresholds make workforce sequencing a governance issue. Board governance plant closure rules should identify who can approve changes to the workforce plan. Reserved matters should exist before local execution starts A decision-rights map should separate scope changes from ordinary execution. The Board can retain customer extensions, total closure funding, major liability assumptions, property decisions, and changes to the final end state. The US closure executive can control daily execution inside those limits. Final OEM commitments stay with the Board when they change exit economics Customer requests can extend the approved perimeter An OEM request to extend production can change labor, inventory, maintenance, logistics, and supplier needs. New service-parts commitments can create the same effect. Delayed tooling transfer or extra premium freight can also move cash and timing. In an OEM customer and Tier-1 automotive supplier relationship, local management should not create a new obligation that changes the approved exit. Four commercial decisions should cross the escalation line Formal closure dates create hard coordination points Virginia Works records that Continental Automotive Systems filed a WARN notice on 1 July 2024 for its Culpeper closure. The notice listed an impact date of 4 October 2024 and 150 affected employees. This example does not suggest a governance failure at Continental. It shows that a US manufacturing plant closure creates formal dates that must match the commercial exit plan. European automotive groups such as Continental and ZF Group, including ZF Active Safety, operate within connected customer and plant schedules. The Board needs visibility when a customer request alters that schedule. The Board owns the cash-to-close envelope, while local management controls approved spending Funding authority should follow the approved closure case The Board should approve the total cash envelope and its core assumptions. Local management then needs authority over normal closure spending inside that envelope. This can include supplier settlements, required staff, site services, inventory disposal, and approved decommissioning. A European company closing US plant operations loses time when routine payments repeatedly return to Europe. Escalation should start when the economics move Benefit obligations can run on a separate clock The Pension Benefit Guaranty Corporation (PBGC) sets a separate timetable for a standard termination of a covered single-employer defined-benefit plan. The Notice of Intent to Terminate generally goes out at least 60 days before the proposed termination date. The same notice generally cannot go out more than 90 days before that date. PBGC rules, ERISA Section 4041, and 29 CFR Part 4041 then require additional notices and filings. The last production day cannot serve as a universal financial completion date. The cash-to-close case should reflect the separate benefit timetable. Employee, environmental and contractual exposure must be quantified before authority moves locally Federal WARN does not cover the full notification analysis The Employment and Training Administration within the U.S. Department of Labor says some states impose their own plant-closing requirements. Those rules can add obligations beyond federal WARN. The facility location therefore matters before management approves announcements, phased exits, or workforce changes. Representation issues require a separate legal check. Local counsel should test actions against the National Labor Relations Act (NLRA) and National Labor Relations Board (NLRB) jurisdiction. Environmental obligations can survive manufacturing The U.S. Environmental Protection Agency (EPA) sets financial assurance rules under the Resource Conservation and Recovery Act (RCRA) for applicable hazardous-waste treatment, storage, and disposal facilities. Regulated facilities must demonstrate financial resources for proper closure. Closure-cost estimates can include safe shutdown and contamination work. Post-closure duties can include monitoring, maintenance, and record keeping. Those rules do not apply in the same way to every automotive factory. The group must establish the environmental status of the specific site. The Board should not assume that production cessation or a property sale ends the exposure. The Barnesville record shows why diligence belongs before the final shift The Georgia Environmental Protection Division site summary identifies the General Tire-Aldora Plant at 160 Aldora Street in Barnesville as Hazardous Site Inventory No. 10057. The record notes regulated-substance releases and required corrective action. This example applies to that site only. It does not imply that other automotive closures carry comparable contamination. For board governance plant closure purposes, residual obligations can affect property decisions, closure funding, and the final end condition. The Board needs those facts before an asset exit. A closure case study separates site activity from group control A
High-Risk Merchant Account Providers: A CFO’s Checklist
A high-risk merchant account is a liquidity position, not a procurement line item. Reserves, settlement terms and termination rights decide how much cash your business can actually access. Here is how six specialist providers compare, and what boards and CFOs should establish before signing anything.
Interim CFO Leadership During International Expansion
Learn how Interim CFOs support international expansion through financial visibility, governance control, and operational coordination.
Interim CFO Support During ERP and Reporting Recovery
Learn how Interim CFOs stabilize ERP and reporting recovery through governance control, reporting visibility, and operational leadership.
Interim CFO Leadership During Carve-Out and Separation
Carve-outs become unstable when standalone finance control is not built fast enough. Here is what Interim CFOs actually do during separation and why it matters.
Interim CFO Leadership During Corporate Restructuring
Corporate restructuring fails when visibility and cadence collapse before plans are executed. Here is what Interim CFOs actually stabilise and how.
Interim CFO Strategies for Working Capital Stabilization
Working capital pressure starts with operational drift, not a liquidity crisis. Here is how Interim CFOs identify and fix the three specific levers that matter.
Why Crisis CFOs Start With a 13-Week Cash Flow Forecast
Crisis CFOs rarely lose liquidity first. They lose visibility first. Here is why the 13-week cash flow forecast is where stabilisation always begins.
Post-Acquisition CFO Gaps: Why the First 100 Days Fail
Post-acquisition CFO gaps rarely start with a major failure. Here is why the first 100 days destabilise and how experienced financial leadership restores control.
Covenant Breach Risk: What PE Sponsors Must Do First
Covenant breach risk is rising across PE portfolios. What sponsors do first determines how much flexibility they preserve.
 EN
 DE
 FR
 IT
 PL
 RO
 CS
 SK
 HU
 ES
 RU
 AR
 SL