
Mondi Brzeźno and Szada Closures: Managing Customer Transfer and Asset Relocation in Packaging Plant Restructuring
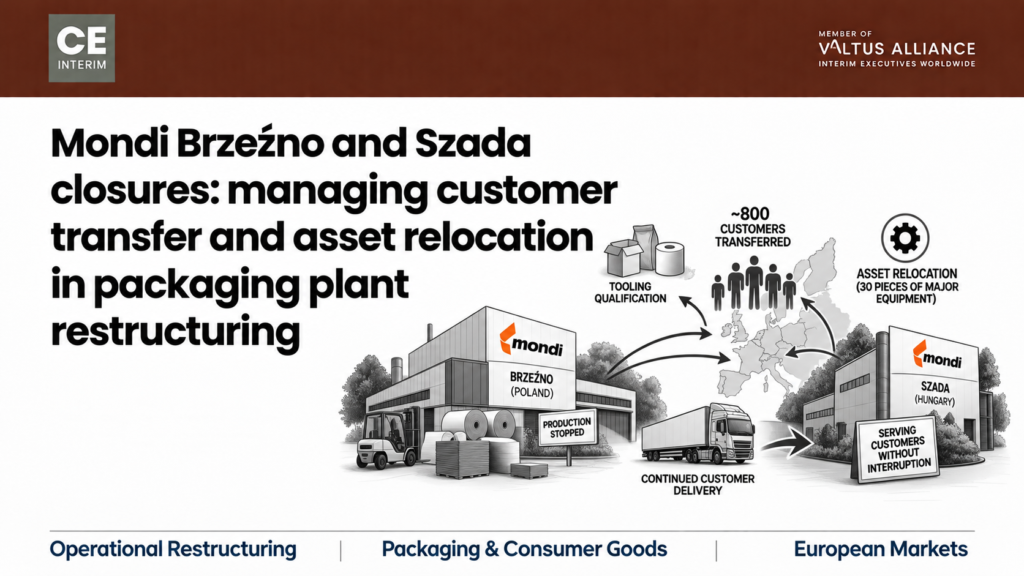
Mondi’s Brzeźno and Szada closures show why customer transfer during a packaging plant closure decides whether the group protects value.
Romania changed wages and taxes. Which changes actually hit your operating case?
In brief Romania changed its statutory wage floor, VAT rate and dividend withholding tax within twelve months. Industrial energy tariffs moved sharply in the same period. Not every change reaches a foreign-owned Romanian subsidiary the same way. The wage floor and energy costs can hit direct payroll and margin. The VAT increase mainly affects domestic sales and working capital timing, not export margin. The dividend tax often does not apply at all to an established EU parent, under the EU Parent-Subsidiary Directive. Four tests establish which changes are real before the board debates closure. Three fiscal shifts in Romania impacting corporate planning cycles When updated projections from a Romanian subsidiary deviate from the annual plan, group finance must evaluate three distinct statutory shifts that landed within a single twelve-month planning cycle: Why group headquarters misreads a Romanian subsidiary’s cost structure Headquarters often misreads a fiscal package by applying a single blended assumption across the business rather than evaluating how individual changes affect specific operations: Four financial tests for evaluating a Romanian subsidiary’s operating case Before any board debates absorbing costs, restructuring or exit, group finance has work to do first. It should run four tests on the Romanian subsidiary, in sequence. Each test uses primary payroll, customs or shareholding records, not a single blended group assumption. Test 1: Assessing the Romanian wage floor increase and pay band compression The government froze the gross minimum wage at RON 4,050 through 30 June 2026. It rises to RON 4,325 from 1 July 2026, under Government Decision 146/2026. This applies to every employer in the country. What varies is how much of the workforce actually sits near that floor. The test is simple. Check what share of headcount earns at or near the floor. Then check how much the new floor compresses the pay bands above it. In a high-volume assembly plant, thirty to forty per cent of headcount may sit on baseline wages. Direct cost then rises immediately. In a precision or electronics plant, entry pay often exceeds RON 5,000 already, so the direct effect stays small. The harder cost is compression. When entry wages rise by decree, technicians and shift supervisors expect a proportional increase too. Grant it, and payroll inflates across the whole structure. Refuse it, and skilled operators leave for local competitors. For a Romanian subsidiary, the wage floor test has to examine the pay structure, not only the headline rate. Test 2: Analyzing the Romania VAT increase on working capital and exports Romania raised standard VAT from 19 to 21 per cent on 1 August 2025, under Law 141/2025. Corporate controllers often fold this straight into margin forecasts. They assume it cuts profitability directly. For an export-focused Romanian subsidiary, that assumption usually does not hold. VAT is a consumption tax that falls on the domestic buyer. The Romanian subsidiary may export finished components to parent assembly lines in Germany, Austria or France, or to European OEMs. Those intra-community supplies carry a zero VAT rate, so the plant does not carry VAT on those sales. Where the increase does bite is domestic procurement, utilities and local contractor invoices. The subsidiary reclaims this later through monthly VAT returns. If the tax authority delays refunds, working capital tightens in the meantime. For an exporting plant, this is a cash-timing problem, not a margin problem, and the two need different responses. Test 3: Evaluating Romanian dividend withholding tax and EU directive exemptions On 1 January 2026, the dividend withholding tax rose from 10 to 16 per cent. Commentators widely reported this as a direct cut to investor returns. For a German, French or Austrian group holding a Romanian subsidiary, the headline rate may not apply at all. This test means checking the shareholding register against the EU Parent-Subsidiary Directive, Council Directive 2011/96/EU. PwC Romania summarises the rule in its statutory guidance. A parent resident in another EU or EEA member state can receive dividends free of withholding tax. The parent must have held at least 10 per cent of the Romanian entity for an uninterrupted year. It also needs valid tax residency certification. A group holding 100 per cent of its Romanian subsidiary for several years keeps an effective rate of zero. The 16 per cent rate reaches private individuals and minority holders below the 10 per cent threshold. It also reaches non-EU structures without a comparable treaty, or entities that have not yet passed the one-year mark. Most groups skip this test on their Romanian subsidiary. They simply assume a six-point cut to repatriated cash, and that assumption is often wrong. Test 4: Measuring industrial energy tariff volatility and technical energy intensity A Romanian industrial manufacturer’s managing director has named volatile electricity tariffs the sharpest pressure on manufacturing competitiveness in 2026. That ranks the tariffs above statutory tax changes. A proposed minimum turnover tax added to the concern. It drew sustained opposition from twelve national employer associations, including the French Chamber of Commerce and Industry in Romania (CCIFER). The test here evaluates a Romanian subsidiary’s technical energy intensity, not a national average. In a foundry, injection-moulding shop or glass line, power can account for twelve to twenty per cent of operating cost. A tariff surge then changes the unit economics directly. In manual assembly or light packaging, energy rarely exceeds three per cent of cost. The same tariff move barely registers there. A single national energy figure hides where the real exposure sits. Key warning signs that a Romanian subsidiary is under financial pressure A board does not need to wait for the annual review to see whether these tests matter. Five signs usually appear first, often in this order. Any one sign on its own is manageable. Two or more together usually mean the Romanian subsidiary needs an independent, on-site review before the board decides anything. First priority for group finance: Establishing verified operational facts Before corporate boards evaluate major strategic choices such as absorbing costs, contract renegotiation, or plant closure, group finance must establish verified operational facts: Deploying
When the CFO says close it and the COO says invest, who breaks the tie?
In brief An underperforming foreign plant splits the Group CFO and the Group COO. The CFO wants closure, while the COO wants investment. This is a CFO COO deadlock, and the board is the only body that can break it. Facts alone cannot decide a strategic question, so boards decide. Resolving a CFO COO deadlock therefore takes four steps, always in the same order. First, an independent fact base. Second, a stress test of both cases against cash, customers and recoverability. Third, a single board vote. Finally, an executive placed on site to execute whichever mandate the board approves. A consultancy resolves the analysis, whereas an executive carries the outcome. How four quarters of CFO COO disagreement cause strategic paralysis The asset first reached the board last year, in the third quarter. It then returned in December and resurfaced again in spring. Today it still sits on the same table, largely unchanged. In other words, this is a CFO COO deadlock that returns every quarter without moving. Both positions hold up, and that is the real CFO COO deadlock in its purest form. Deferring the decision is the one choice neither executive has to own personally. Consequently, faced with two credible cases, the board commissions another sensitivity analysis instead of deciding. Deferral then becomes the policy, and it carries a cost every quarter it continues. Cross-border governance: Why distance worsens a CFO COO deadlock On a domestic site, a director can walk the floor in an afternoon and settle the question directly. The cross-border corridor, however, changes this. A German, Austrian, Swiss or French parent may own a plant in Czechia, Poland, Hungary or Romania. Distance limits what headquarters can actually verify, and that is exactly where a CFO COO deadlock takes root. Why CEE wage pressure deepens a CFO COO deadlock Wage pressure across Central and Eastern Europe adds to the CFO COO deadlock. KPMG and the Committee on Eastern European Economic Relations found something clear. Low labour costs alone no longer justify a CEE plant. Technical labour is tightening and wages are rising, so a mediocre operation can no longer hide behind cost arbitrage. When margins compress, the CFO sees a location failure, whereas the COO sees a fixable shortfall. Both readings can hold some truth. That is exactly why the board, rather than either function, has to decide which one governs. 5 key warning signs of a board deadlock in a foreign subsidiary Boards rarely name an impasse directly. Instead, a board deadlock foreign subsidiary shows up through five recurring signs. Each one marks a CFO COO deadlock that has already outlived its usefulness. Once several of these signs appear together, another internal committee will not break the CFO COO deadlock. It only spends cash runway the board still has left to work with. The 4-stage framework to resolve a CFO COO deadlock Resolving who decides plant closure needs a sequence, not a better meeting. Someone must own the facts, and someone must own the execution once the board decides. A consultancy resolves the analysis, whereas an executive carries the outcome. Skipping a step therefore leaves the CFO COO deadlock exactly where it started. ● Stage 1: Establish an independent, verified operational fact base Internal accounts carry each function’s bias, so they cannot settle the dispute alone. An independent executive on site, however, establishes real numbers within weeks. These include true overall equipment effectiveness, actual scrap rates, the real bottleneck, unbundled customer margins, a thirteen-week cash forecast, and verified severance and supplier liabilities. ● Stage 2: Stress-test closure vs. investment cases across core criteria The board then tests four things: cash runway and liquidity depth, customer contractual exposure, operational recoverability, and a net cash-to-close comparison. Boards routinely underestimate closure costs. At the same time, they overestimate turnaround speed. That is why this stage comes before the board accepts either case. ● Stage 3: Hold a decisive board vote on plant closure or turnaround Independent interim executives never make the strategic call to close or invest. Instead, that decision belongs to the board or the investment committee alone. Facts do not decide a CFO COO deadlock. Boards decide it. ● Stage 4: Appoint an interim executive to carry out the board mandate Internal management is rarely the right team to carry out a decision it fought over, so the board appoints instead. An interim CFO fits where reporting was the problem. Where the answer is operational turnaround, an interim COO fits. If cash is the binding constraint, an interim Chief Restructuring Officer fits. For a controlled closure, an interim Managing Director or Plant Manager fits. Meanwhile, a CE Interim Partner stays involved throughout, holding governance and escalation alongside the interim executive, and manages the handover to permanent leadership once the mandate is complete. European manufacturing trends: Rising financial and operational pressure on foreign plants A CFO COO deadlock like this one reaches beyond a single plant. In fact, it is spreading. The CLEPA Data Digest 24, published in January 2026, recorded a stark number. European automotive suppliers announced more than 104,000 job reductions across 2024 and 2025 combined. Energy tariffs, supply chain realignment and price competition drove the cuts. As a result, subsidiaries that once delivered reliable low-cost output are now falling into distress themselves. Each one carries its own CFO COO deadlock waiting to surface. Private equity faces a parallel pressure. European private equity exit volumes fell to 872 transactions in the first half of 2026. That is down from 1,210 transactions a year earlier. The EY Global Private Equity Exit Readiness Study 2026 found a pattern behind those numbers. Sponsors increasingly hold assets that remain operationally viable. Even so, those same assets face trapped liquidity and stalled exits from valuation mismatches. An operating partner therefore cannot afford an open-ended CFO COO deadlock inside a holding period like that. Protecting enterprise value needs a decisive intervention rather than another quarter of analysis. Case study: How a Tier 1 automotive supplier resolved a 9-month CFO COO deadlock
When German headquarters cut costs, the Czech subsidiary is not in the same market
In brief When a German parent group launches a cost reduction programme, corporate finance often sets one savings target. It then applies that target to every foreign entity, including any Czech subsidiary. That is usually where the mandate fails. Czech industrial sentiment currently sits at a five-year high. German sentiment stays weak, and the two economies are pulling apart. The Czech subsidiary’s real constraint is usually energy and skilled labour, not the wage bill German headquarters wants to control. Testing which parts of a German cost mandate actually fit Czech conditions is a board-level judgement. It is not an administrative rollout. Getting it wrong can turn a savings target into a supply chain crisis within weeks. The trigger: How a German cost target reaches the Czech subsidiary The pattern usually starts in Germany. Margins come under pressure. Overheads rise. The executive committee approves a group wide cost containment mandate. Corporate finance calculates a single savings percentage, often eight to twelve per cent of operating expenditure. It then applies that figure uniformly across every foreign entity. The Czech subsidiary receives its allocated figure inside the monthly reporting pack. The number arrives detached from the plant’s actual operating conditions in Bohemia or Moravia. Nobody at headquarters has recently walked the shop floor. Nobody has reviewed the energy contract or checked the order book against current capacity. This is not carelessness. A parent under pressure at home reasonably wants every part of the group to contribute. The problem starts when that instinct reaches the Czech subsidiary unchecked. Nobody has first tested whether its cost base and market position resemble Germany’s at all. German parent defensive planning meets Czech manufacturing reality Executive committees rarely see this gap in a single report. The two economies are now moving on different paths. In Germany, industrial confidence remains subdued. The DIHK Economic Survey gathers data across roughly 26,000 enterprises. It found that domestic labour costs are the top risk factor for a record 59 per cent of German companies. Research by Strategy& and PwC puts German industrial labour costs at roughly 30 per cent above the European Union average. The DIHK spring survey adds a second data point. Only 23 per cent of German industrial companies plan to raise capital investment in 2026. Corporate leadership in Germany is acting defensively, and a frozen capital budget is one visible result. None of this describes the Czech subsidiary’s own market. Applying German defensive logic to Czech operations risks a basic error. It treats a symptom of the German economy as if it were a Czech one. Why a uniform cost reduction target misreads the Czech subsidiary Czech manufacturing sentiment tells a different story. The AHK Czechia economic survey covers 125 member and other German enterprises. It found that business sentiment on the Czech economy has reached its highest level in five years, with nearly every indicator rising. The managing director of AHK Czechia summarised the shift directly: it no longer holds true that the Czech economy catches pneumonia when Germany catches a cold. DTIHK findings confirm the same signal from a different angle. An eight-year downward investment trend has halted. Renewed industrial modernisation has replaced it. Germany Trade and Invest’s own assessment states plainly that Czechia is decoupling from the German economic cycle. Crucially, Czech plant directors worry about a different risk entirely. In the DTIHK findings, industrial leaders in Czechia rated energy prices and supply as their single biggest risk to competitiveness. Labour costs came second. Volatile power tariffs, the capital cost of automation and a shortage of technical staff constrain the Czech subsidiary. Wages matter far less. A cost programme built around German labour arithmetic targets the wrong constraint. How executive boards recognise cost target mismatches in foreign entities Executive committees rarely spot this divergence through a standard monthly pack. By the time it shows up in the numbers, it has usually already cost the business something. A handful of concrete signs tend to appear first. German updates describe headcount containment and capacity reduction. Reports from the Czech subsidiary ask for extra shifts, machinery overhauls and recruitment instead, to protect existing customer commitments. Margins erode through unscheduled expedites. The plant appears to respect its monthly ceiling on paper. Underneath that, unplanned downtime and premium freight quietly multiply under different budget lines to meet delivery deadlines. Local management stops raising operational constraints with corporate controlling. It concludes headquarters will not adjust the target regardless of what it hears. Skilled technicians, shift supervisors and production engineers start leaving for competitors paying market rates. Customers eventually bypass the local entity altogether. They raise delivery or quality complaints directly with group executives instead. Any one of these signs deserves attention. Two or more appearing together usually means the target and the Czech subsidiary’s real operating conditions have already separated. What a credible cost programme response requires in Czechia Resolving the mismatch starts with an honest fact base, not a renegotiated percentage. The board faces key choices and steps to resolve the mismatch: Where the relationship between parent and local management remains strong, this can stay an internal conversation. Both sides need to trust the data first. Group executives can then visit the plant and examine supplier contracts. They can audit the shop floor and recalibrate the target together with local leadership. Internal resolution becomes harder to sustain under three specific conditions. At that point, an independent executive on site is usually the fastest route back to one shared set of facts. The cross-border corridor bridge: German headquarters, Czech subsidiary, and accountable interim leadership An interim COO or interim managing director gives the Czech subsidiary operational and statutory authority in one place. That executive reports to the same board that set the original target. The interim leader carries no stake in past investment decisions or corporate politics. That independence allows a clear audit of machine availability and a clear view of the true production bottleneck. Supplier terms then get renegotiated against current conditions, not the assumptions behind the original mandate. This
Electrolux Jászberény Plant Closure Operational Execution During an Eight-Month Wind-Down
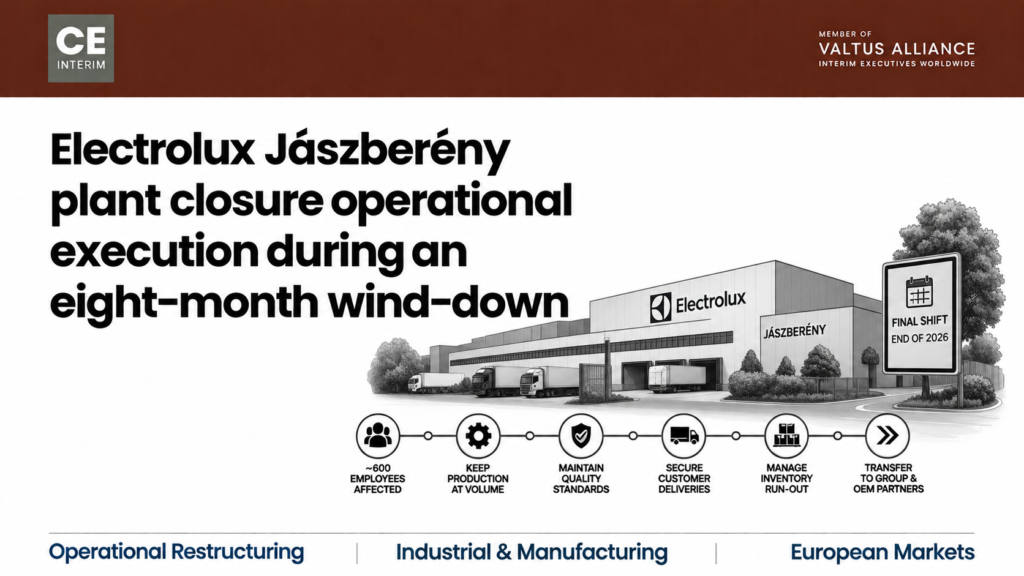
What the Electrolux Jászberény plant closure demands from plant leadership before the final shift ends.
Hungary labour costs 2026: has your plant’s business case kept pace?
In brief Hungary labour costs 2026 rose 16.4 per cent in whole-economy hourly terms in the first quarter. That is the steepest increase anywhere in the European Union. For a German-owned plant built on a wide labour discount, this is not automatically a reason to exit. Hungary’s absolute hourly labour cost still sits well below the Western European baseline. Hungary labour costs 2026 raises a narrower question. Does the plant’s productivity justify its new wage floor, and if not, what has to change first. How Hungary labour costs 2026 exposed an old business case The issue usually reaches the board through one line in the monthly management pack. The annual plan assumed a wage settlement of five or six per cent. The finalised agreement landed in double digits instead. Direct labour cost is over budget. Gross margin is falling. The plant is asking for an emergency budget revision. Hungary labour costs 2026 is the reason that request now lands on the board’s desk. Behind that variance sits a harder question. Many groups built their Hungarian plants on one justification: low operating cost. For years, a wide labour discount absorbed ordinary weaknesses: average scrap rates, average machine utilisation, deferred maintenance. The plant was affordable rather than efficient, and affordable was enough. Now that Hungary labour costs 2026 has narrowed the discount, it no longer is. Evaluating 2026 Hungary Labour Costs Across the Germany-Hungary Manufacturing Corridor A German owner assessing a Hungarian plant from headquarters holds two facts that pull in opposite directions. Both are correct at the same time. Hungary labour costs 2026 rose 16.4 per cent year on year in the first quarter. France recorded 1.8 per cent over the same period, and Malta 1.3 per cent. That marks a permanent shift in the local cost base, not a one-year anomaly. But in absolute terms, Eurostat puts average hourly labour costs in Hungary at EUR 15.2 in 2025. The EU average stands at EUR 34.9. Germany’s own figure exceeds EUR 45.0. A board that reads only the growth rate concludes the plant has become expensive. A board that reads only the absolute figure concludes nothing has changed. Both readings miss the point on their own. Hungary labour costs 2026 sits precisely in that gap. That is exactly where the wrong decision gets made. Labor Market Dynamics: Skill Shortages and Wage Inflation in Hungary 2026 Hungary labour costs 2026 is not only a cost story. It is also a labour availability story, and the two compound each other. The annual KPMG and Ost-Ausschuss survey covers German companies across Central Europe. It found that 38 per cent of respondents still cite low labour costs as a regional advantage, up five points. But qualified labour availability fell nine points to 28 per cent. The single largest advantage respondents named, at over half, was now the attractive local sales market rather than cost. Automotive and battery investment clusters in hubs such as Gyor, Szekesfehervar and Debrecen. It competes directly for the same technical labour pool the incumbent plant depends on. A cost mandate from Munich or Frankfurt often ignores that context. It assumes the plant can simply hire its way back to the old wage band. Headquarters understandably wants a fast return to budget. But the labour market the plant recruits from has moved. A target set against last year’s assumptions asks local leadership to solve today’s problem with tools that no longer exist. Hungary labour costs 2026 still needs a plant-level answer, not a headquarters-level one. Key Warning Signs Your Hungarian Manufacturing Plant Is Facing Labour Cost Risks in 2026 Five signs matter here, read together rather than alone. They show whether Hungary labour costs 2026 has moved from a budget variance to a structural problem. Five key warning signs show whether labour cost increases have moved from a budget variance to a structural problem: Taken together, these signs confirm that Hungary labour costs 2026 has become the board’s problem now, not only the plant’s. Operational Strategy: Responding to Rising Hungary Labour Costs in 2026 Once two or more of these signs appear, the response should change. It is not a headcount target set from outside the plant. It is a re-underwriting of the business case from first principles. Someone with authority over both the numbers and the shop floor has to run it. Three questions need answers, in sequence, not all at once: Hungary labour costs 2026 does not, on its own, tell a board what to do next. Establishing that first fact base has to happen before the board argues about which path to take. The fact base means an honest, verified picture of cash consumption, order book and machine capacity. It also has to capture the strength of local leadership. Skipping straight to the argument creates two risks. A hiring freeze lands on a labour shortage, or a closure threat lands on a fixable operational problem. Hungary labour costs 2026 rewards whichever board establishes its facts first. It will not be the last shock this plant absorbs. Bridging the Gap Between Headquarters Strategy and Hungarian Plant Operations Hungary labour costs 2026 affects both sides of this corridor, though not in the same way. Group finance in Germany usually works from an aggregated monthly pack that shows the variance but not its origin. Its instinct, tighten cost control and demand a plan, is a reasonable first response to a budget miss. Local plant leadership usually holds a different, equally reasonable instinct. It protects customer delivery at almost any cost, because a missed OEM shipment is the more immediate, more visible failure. Neither instinct is wrong on its own terms. Pursued separately, without a shared fact base, the two instincts can pull the plant in opposite directions. That happens at exactly the moment it can least afford it. An interim executive placed inside the plant reports to both sides on the same verified numbers. That lets headquarters keep capital discipline without removing the local authority the recovery actually needs. Case Study:
PetCenter: how an interim crisis manager acquired a distressed retailer in the Czech Republic
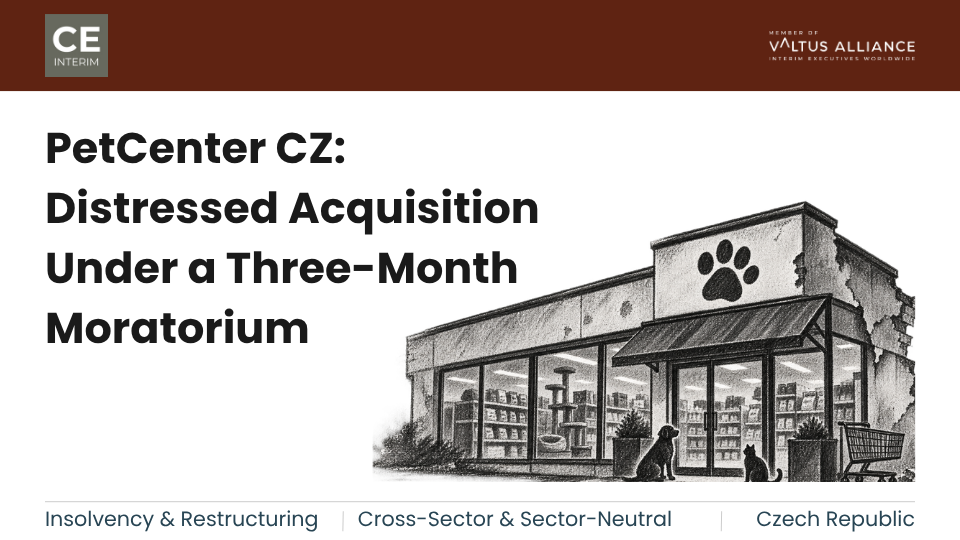
How an interim crisis manager led a distressed acquisition in the Czech Republic: PetCenter’s court moratorium, lease reset and supplier recovery.
Industrial margin squeeze in Central Europe: when should headquarters initiate workforce restructuring in Romania?
In brief Wage inflation, energy costs and customer price freezes can push a Romanian subsidiary’s variable costs permanently above its contribution margin. At that point, workforce restructuring becomes the only measure that restores profitability. Overtime bans, hiring freezes and discretionary cuts slow the cash burn. They rarely close the gap. This article sets out five operational conditions that confirm when voluntary cost measures run out. It also shows how an on-site Interim Chief Restructuring Officer executes compliant collective redundancy under the Romanian Labour Code. Customer delivery continues without disruption. Industrial restructuring drivers in Central European manufacturing For two decades, Western European industrial groups built manufacturing hubs across Romania. Timișoara, Arad, Sibiu, Brașov and Ploiești all grew this way. The original case was simple. Skilled engineering and technical labour cost a fraction of Western European rates. That advantage has narrowed. At the same time, Western European automotive and industrial customers face their own margin pressure. A Romanian plant can usually absorb one of these pressures alone. Wage inflation, energy volatility and customer price freezes together are different. That combination is structural, not cyclical, and it is what eventually makes workforce restructuring unavoidable. Why boards delay plant restructuring: the incremental savings trap Corporate boards rarely move straight to workforce restructuring. The instinct to try everything else first is reasonable. Directors remember what it cost to recruit and train the Romanian workforce. No board wants to disrupt a plant it has invested in for years. So headquarters instructs local management to find savings first. Each measure is sensible on its own terms. On a fixed-shift automated production line, though, they add up to very little. The plant keeps operating below its breakeven capacity utilisation while months pass. By the time the board accepts that incremental measures have failed, the subsidiary has usually burned through its operating cash reserves. Workforce restructuring then happens under emergency conditions rather than as a planned decision. Recognising the threshold earlier keeps the decision inside the board’s control. Statutory framework for workforce restructuring in Romania Workforce restructuring in Romania sits inside a strict statutory framework. The Romanian Labour Code, Law no. 53/2003, regulates collective dismissals, concediere colectivă, against defined thresholds. Article 68 sets the trigger. An employer with 100 to 299 employees crosses it by dismissing at least 10% of its workforce inside a 30-day window. An employer with 300 or more employees crosses it at 30 dismissals in the same window. Once that threshold applies, the employer must notify and consult the representative trade union or elected employee representatives. The consultation covers ways to limit dismissals, social support and retraining. The employer must also notify the Territorial Labour Inspectorate, the ITM, and the County Agency for Employment, the AJOFM, at the same time. At least 30 calendar days must then pass before individual termination notices go out. Employees keep a statutory right to re-employment for 45 calendar days if the company re-establishes their position. Romanian labour courts apply this process strictly. A single defect in the consultation timeline, or in the selection criteria, can void the dismissals. The company then owes retroactive salary and must reinstate the workforce it restructured. Getting the sequence right the first time matters more in Romania than in almost any other Central European jurisdiction. Operational risks in plant restructuring overlooked by headquarters Beyond the legal process lies a risk that headquarters rarely notices until it has already progressed. This leaves the plant with a less experienced team at the exact moment it needs its best people. Incumbent Romanian plant directors usually built their careers and relationships inside that community. Understandably, they find it hard to propose cuts to people they know personally. This is not a sign of weak management. It is a natural response to a genuinely difficult position. It is also exactly why the decision needs an executive who does not carry that local history. Harvard Business Review research on workforce reductions makes the same point: delayed, incremental downsizing damages culture while it extends financial distress. Once the plant confirms structural overcapacity, the board needs an objective, verified operating plan, not a locally negotiated compromise. Workforce restructuring in Romania: five operational thresholds Boards and group operating officers need clear, objective criteria for knowing when non-headcount savings run out. Structural workforce restructuring becomes the right call once five conditions converge. No single condition on its own is enough. Physical asset utilisation stays below 65% to 70% for three consecutive quarters. No contracted volume recovery is forecast for the next twelve months. Running a three-shift pattern against a two-shift order book is exactly the situation that makes workforce restructuring the only lever left. Direct and indirect labour cost keeps climbing as a share of cost of goods sold, even while output stays flat or falls. Local wage rises outpace customer price indexation. They also outpace machine productivity gains. Headcount needs re-baselining, which is what workforce restructuring actually does. The plant has already ended agency staffing contracts, cut overtime and used up its statutory flexible-hours allowance. Contribution margins remain negative regardless. No variable-cost lever remains to pull. This is the clearest single signal that workforce restructuring cannot wait. The subsidiary can no longer fund payroll and vendor payments from its own operating cash flow. Group treasury covers the gap month after month. That subsidy has become routine rather than exceptional, and it will not stop until workforce restructuring changes the underlying cost base. When asked for cost-reduction scenarios that include headcount, local leadership tends to offer only cosmetic cuts. Administrative roles get trimmed. Direct manufacturing shifts stay untouched. McKinsey’s analysis of manufacturing profitability in high-inflation environments reaches the same conclusion: restructuring has to match real customer demand, not a hoped-for recovery in volume. That discipline is exactly the standard workforce restructuring has to enforce. Executing industrial restructuring: the role of an interim CRO Downsizing a workforce made up of neighbours and long-standing colleagues is not a fair task for the incumbent local manager. Workforce restructuring like this needs authority that cannot sit with
Keeping a Slovak plant operating through a multi-country divestment
Each transaction in a divestment programme moves through signing, approval and completion on its own timetable. The plants have to keep
producing across all of it.
How COOs lead a failed ERP implementation recovery before production halts
In brief A failed ERP implementation recovery inside a Czech manufacturing plant is an operational emergency. It is not a task to leave with the systems integrator. When a go-live fails, inventory stops posting and pick lists freeze. Finished goods cannot legally leave the dispatch dock. The Board’s real question is simple: who takes command while the team repairs the database? This guide sets out the four-phase sequence for a failed ERP implementation recovery that an Interim ERP Programme Director follows. Phase one is a manual bypass that protects customer deliveries. The team then repairs master data and stabilises core transactions, before handing the plant back once it runs cleanly. The trigger: warehouse gridlock in the first ten days after cut-over An industrial ERP rollout rarely fails quietly. The failure usually appears in the first ten days after cut-over, not months later. A steering committee in Munich, Vienna or Zurich signed off after months of testing. Day three looks different. Picture a components facility near Plzeň, Liberec or Pardubice. The new system loses contact with the physical plant. Forklift drivers scan bins the software declares empty. Production lines pause, because the ERP cannot generate replenishment orders. This is a failed ERP implementation recovery in its earliest, most physical phase. Finished goods pile up in the warehouse aisles. Outbound shipping cannot generate freight documentation or customs dispatches. Within three days, the loading dock stops moving. A Tier 1 customer’s assembly line in Germany faces its own line stop. The systems integrator argues the software works and blames local change management. The Czech plant director wants an immediate rollback, a move that would write off millions and stall statutory accounting. The COO now owns a shop-floor emergency that started as a software project. A failed ERP implementation recovery has to begin at once. Challenges in Managing Cross-Border ERP Recovery Projects Recovering a failing ERP deployment inside a Czech manufacturing subsidiary means untangling three problems at once. They are data architecture, local operations, and corporate governance. None of them responds to the same fix. A failed ERP implementation recovery does not stall on the technology alone. It stalls on who has the authority to decide once systems stop behaving as designed. Resolving Discrete Manufacturing Master Data Errors in ERP Recovery This is where a failed ERP implementation recovery either succeeds or drags on for months. Discrete manufacturing has little tolerance for approximate data. Three structural faults cause most failures. Fixing these three faults is the Interim ERP Programme Director’s job, not the Board’s. The Board’s task is narrower: grant the authority to freeze changes and reallocate people while that work happens. These three faults are where most of a failed ERP implementation recovery’s early effort goes. Managing Cross-Border Governance and Statutory Compliance Risks A second problem sits above the data: cross-border governance, where a failed ERP implementation recovery either gains momentum or stalls. Corporate headquarters usually treats the rollout as an IT upgrade, run by external consultants from a distance. On-site, plant personnel see it as an outside burden that stops them from making parts. Neither view is wrong. Each side sees a different part of the same failure. The relevant rule sits in the Business Corporations Act, Act No. 90/2012 Coll. Together with local tax accounting standards, it means goods cannot leave the premises without compliant tax and delivery notes. If the software cannot generate valid paperwork, management cannot legally dispatch goods, whatever the shop floor’s physical capacity. Gartner and industry analysts find that 55% to 75% of ERP projects in manufacturing fail to reach their targets. Discrete plants suffer the highest post-go-live disruption. McKinsey & Company reports that over 70% of digital transformations fail to deliver the value expected. This is the operating reality a failed ERP implementation recovery works inside, not around. Five Operational Indicators That Require Immediate ERP Crisis Management Routine post-launch friction and a structural system failure look alike in a failed ERP implementation recovery’s first few days. Five signs mark the point where the crisis threshold arrives. Any one of these five signs marks a failed ERP implementation recovery already underway, not routine noise. The Four-Phase ERP Go-Live Recovery Framework Halting the failure does not need more programmers writing custom code. It needs an on-site executive who understands both the shop floor and enterprise architecture. An Interim ERP Programme Director, or Recovery Director, leads the failed ERP implementation recovery from day one. This executive takes direct operational command. The interim leader ends the finger-pointing between corporate IT and local plant leadership. To resolve the crisis, the organisation needs a proven, mandate-matched executive. That executive must be ready to start within 72 hours of the completed mandate brief. Phase 1: Establishing Manual Shipping Bypasses and Code Freezes The first week has one objective: keep the customer’s lines running and clear the physical dock. The interim leader authorises a temporary, paper-based shipping procedure. Trucks move on verified physical counts while the team repairs the software. All unverified IT customisations freeze without delay, so the database stops acquiring new errors. A twice-daily triage meeting brings together the plant director, warehouse lead, corporate IT head and lead integrator. It prioritises fixes strictly by production impact. This is phase one of the failed ERP implementation recovery. The COO’s own decision here is narrow but critical. Approve the manual bypass and the code freeze on day one, then let the interim director run the sequence. Phase 2: Cleaning Master Data and Reconciling Physical Inventory Once the team secures shipping, it repairs the gap between the database and the physical plant. A targeted weekend stock count reconciles quantities and bin locations for the highest-volume parts. The results become the new verified baseline. The team then corrects flawed routing times, scrap multipliers and backflush triggers. It simplifies the warehouse hierarchy too, so virtual staging locations no longer mislead forklift operators. This second stage of the failed ERP implementation recovery is where the system starts telling the truth again. Phase 3: Stabilising Order-to-Cash, MRP, and
 EN
 DE
 FR
 IT
 PL
 RO
 CS
 SK
 HU
 ES
 RU
 AR
 SL