En resumen
A manufacturing subsidiary can report a profit and still ask headquarters for cash every quarter. Profit follows the work performed, but cash follows the customer's payment. That is why subsidiary cash flow can stay negative in a profitable plant. Fund the verified, essential obligations first. Then sort each euro requested into structural need, external timing or an avoidable obstacle. Give each obstacle an owner, a date and a review, and release the next transfer alongside those actions.
Managing Month-End Subsidiary Funding Requests
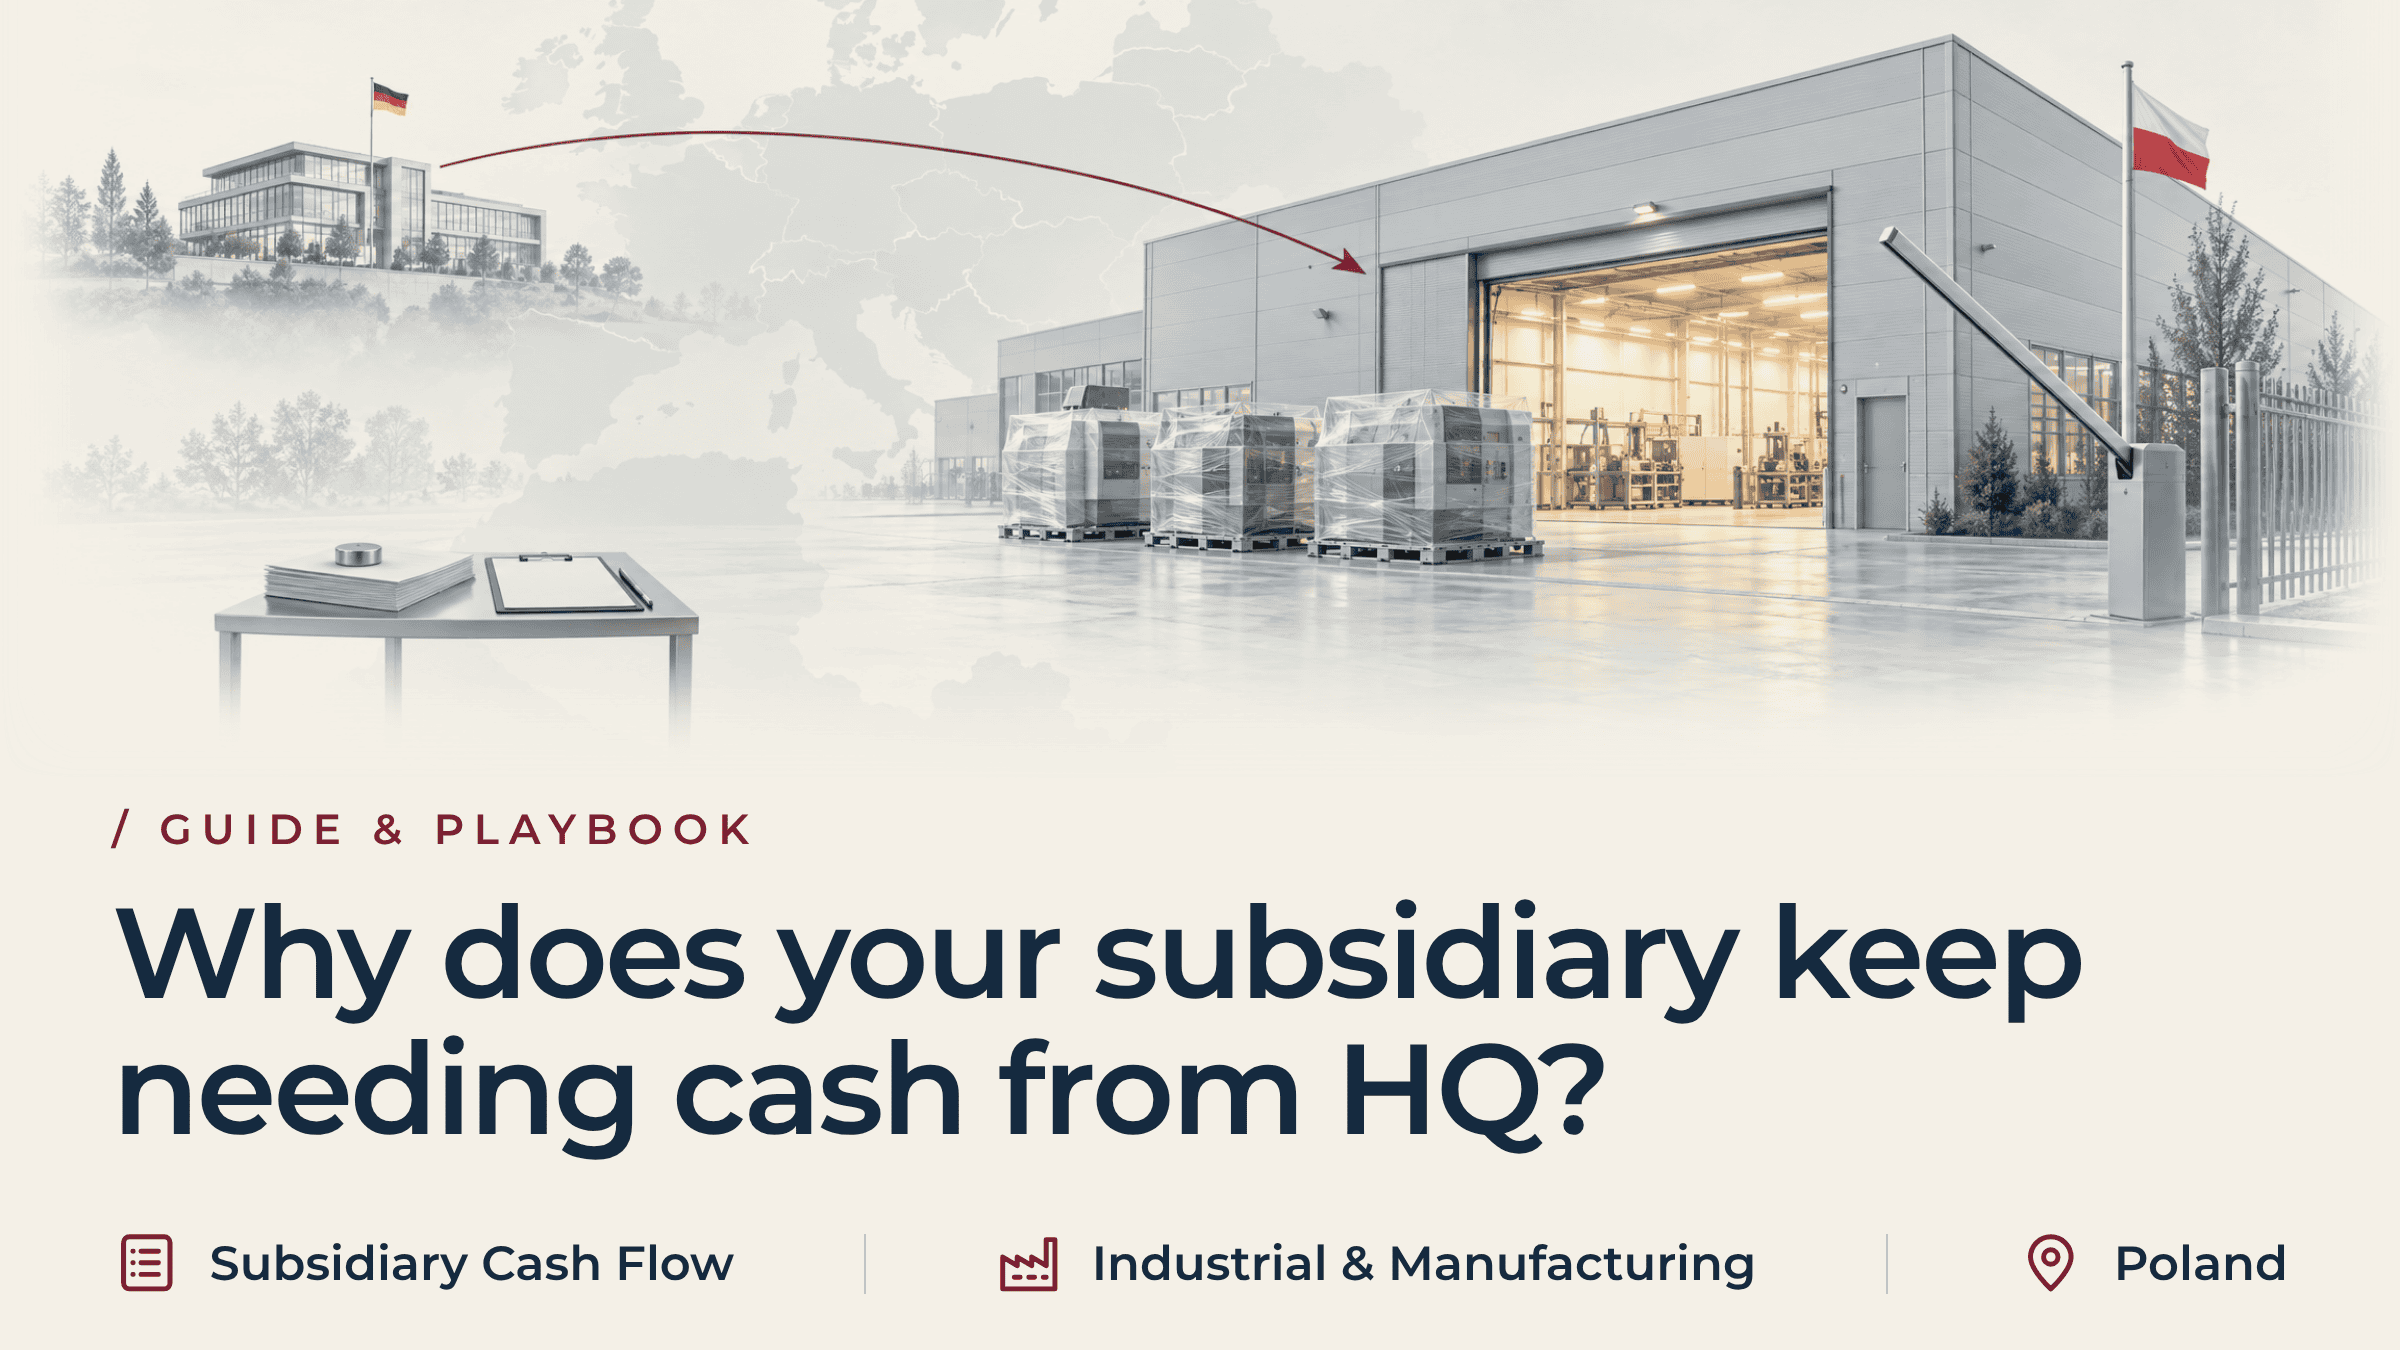
The message comes from the managing director of a Polish plant. Payroll and the supplier run fall due at month-end, and the bank balance will not cover both. The accounts show an operating profit, a full order book and output on plan.
Group leadership faces a fair dilemma. A transfer keeps the plant running but may fund the same issue next quarter. Withholding cash protects discipline but risks supplier delivery holds and a stopped customer line.
Many headquarters teams approve the transfer and ask for a 13-week cash forecast. We understand why. But a forecast shows when cash will leave. It does not explain why cash is not arriving.
A recurring cash shortfall is a question to resolve, not proof of weak management. Every headquarters funding request raises two questions: what must the plant pay now, and what keeps creating the need?
Key Drivers of Divergence Between Subsidiary Profit and Cash Flow
A German or French sales team often negotiates the customer terms. The Polish plant delivers against them and carries the cash consequence. Its leader cannot settle a claim that rests on a contract signed elsewhere.
Information Gaps Between Headquarters and Manufacturing Plants
Headquarters sees ledger lines: receivables, inventory and payables. The plant sees machines awaiting sign-off, disputed freight charges and missing quality documents. Each view is accurate, and each is incomplete.
Accounting Differences Between Operating Margins and Cash Reserves
The IFRS Foundation's overview of IAS 7 describes how a cash flow statement shows changes in cash and cash equivalents. A plant can report a healthy margin while its subsidiary cash flow stays negative. The cash sits in finished goods, unbilled work and unpaid invoices.
Impact of External Market Factors and Late Customer Payments
Intrum's April 2026 report covered 8,385 respondents in 20 European countries. It encontrado that 62 per cent say customer payment delays lead them to pay suppliers late. The EU Payment Observatory's July 2026 analysis notes that many payment delays stem from information gaps or power imbalances. An experienced CFO funds that external part as a bounded facility, separate from the avoidable part.
Identifying Avoidable Subsidiary Funding Requirements
Subsidiary funding requirements with an operating cause tend to show four indicators.
-
Profit without cash. Operating profit stays positive while operating cash flow stays negative for several quarters.
-
Finished work that cannot be billed. Completed assemblies wait for a customer certificate or an approved change order.
-
Split commercial authority. The plant delivers, but headquarters key account managers hold price, terms and invoice settlement.
-
Quiet supplier stretch. Supplier payments drift later, which risks delivery holds and weakens Group purchasing terms.
None of these signs proves failure. Each tells the Group CFO where to look first.
Financial Risks of Delayed Capital Allocation and Escalation Protocol
Each unexplained request can cost Group more than the transfer. A time-pressured approval is understandable, but it releases cash with no agreed cause. Board and owner confidence in the plant's numbers can weaken. Suppliers can tighten terms, customers can escalate to Group, and plant managers can lose authority with their teams.
A second consecutive request without a category-level explanation goes to the Group CFO personally. A third goes to the Board, as a choice between an internal owner and an interim executive. Explained requests do not escalate on count alone.
Immediate Action Steps for Processing Cash Requests
Funding the plant and fixing the cause can run together.
-
Fund the verified, essential obligations. Payroll, critical suppliers and statutory payments come first.
-
Reconcile the request to the factory floor. Trace each euro from the ledger to a machine, a certificate or a disputed invoice.
-
Sort each euro into three categories. Structural need covers planned investment and seasonal working capital. External timing covers agreed customer terms and undisputed late payment outside the plant's control. Avoidable obstacles are gaps the plant or Group can close, such as unbillable work or an unescalated dispute.
-
Name an owner and a date for every obstacle. One person, one action, one review.
-
Release the next transfer alongside those actions. Do not tie essential funding to a recovery target nobody has tested.
More headquarters control improves visibility, but extra approvals can slow the plant decisions that release cash. Establish the fact base first, then settle decision rights. Forecast refinement and the structural items can wait until the team clears the avoidable items.
Subsidiary Funding Explanation Record Framework
Ask the subsidiary to complete one record for each request. The rows below are illustrative.
| Category and need | Evidence | Funding decision | Operating action | Propietario | Next review |
|---|---|---|---|---|---|
| Structural: planned investment and seasonal working capital | Approved capex plan, demand history, firm call-offs | Fund to schedule, or through a bounded facility | Track milestones; match stock release to call-offs | Plant managing director | Mensualmente |
| External timing: customer terms and late payment | Contract terms, payment history | Fund a bounded facility for the gap | Compare customer and supplier payment terms | Group CFO | Trimestral |
| Avoidable: completed work awaiting acceptance | Completion logs, open items | Fund direct labour and material | Clear acceptance criteria with the customer | Plant operations director | 7-day review |
| Avoidable: contested customer invoice | Ageing ledger, dispute notices | Fund essential obligations; agree a settlement limit | Joint session: account sponsor, plant finance, customer purchasing | Group key account lead | 10-day review |
A bounded facility is a funding limit with a named purpose and an end date. The Board sets it, Group treasury chooses the instrument and currency, and the plant draws on it. The record does not make essential funding conditional.
Assigning Ownership for Cash Conversion Management
Start with the internal option. Interim leadership becomes relevant when the cause crosses manufacturing, key account sales, customer teams and treasury. It applies when no one has the authority and time to lead. An Interim CFO then takes a defined mandate. CE Interim assesses each executive against that mandate before the client decides. The executive establishes one fact base, secures decisions from the people who hold them and verifies progress. The mandate sets four terms before the first day.
-
Sponsor. The Group CFO, with one reporting line.
-
Decision rights. The executive holds a written authority to settle customer disputes up to an agreed limit. Customer terms stay with headquarters commercial leaders, who answer for the cash consequence of those terms.
-
Gobernanza. A Partner reviews the fact base and any escalation at agreed intervals. A Board route exists if a decision-holder does not act.
-
Entrega. The cash conversion work passes to the Group controller or local finance lead. The trigger is two consecutive requests with a category-level explanation and no avoidable item open past its review date.
The Group CFO or Board keeps the funding decision, and the plant keeps operating decisions. CE Interim connects the two sides without acting as either side's advocate.
Case Study: Managing Cash Flow in a Cross-Border Subsidiary
A German mid-market industrial machinery manufacturer operated a major assembly facility near Wroclaw, Poland. Over nine months, the Polish subsidiary requested three separate emergency liquidity injections totalling €3.8 million. It reported steady 8 per cent operating margins throughout.
Each time, the accounts showed a profit and the bank account showed a gap. Each transfer won approval under time pressure with no agreed cause. The shortfall recurred roughly once a quarter, and nobody could name its driver.
Group leadership initially assumed local management was failing to enforce supplier payment terms or struggling with inflationary raw material costs. That was reasonable, because the accounts gave no reason to look elsewhere.
Key Findings from the On-Site Operational Review
The on-site review found two operational bottlenecks behind the cash shortfall. Neither appeared on group balance sheet reviews.
First, €2.1 million of completed equipment sat on the factory floor. Production had declared the assemblies finished. Customer quality engineers had not signed the final site acceptance certificates because of minor control-software calibration adjustments. Contracts prohibited invoicing before signed acceptance, so the plant could not bill the work.
Second, €1.4 million in issued receivables remained unpaid by a primary German OEM customer, which was withholding payment. Freight surcharges on shipping invoices did not match the master procurement agreement that headquarters sales directors in Munich had negotiated. Local Polish finance staff had sent standard dunning letters for four months. They did not know the customer's accounts-payable department had flagged the invoices as commercially contested.
Together, the two blockages account for €3.5 million of the €3.8 million requested, or 92 per cent. Both are avoidable. The remaining €0.3 million needed its own review. The ledger showed a receivable, while the customer's system showed a dispute. Neither blockage was a treasury problem, and each needed a decision from someone outside finance.
Implementation Strategy for Interim Finance Leadership
An interim finance leader stepped into the facility and worked across the plant, the customer and headquarters sales. The mandate gave site and customer access. It also gave authority to convene the Munich sales team and a reporting line to the Group CFO. The work ran in sequence.
-
Reconcile first. The executive matched the three transfers to the ledger, the factory floor and the customer file. Each item went into one of the three categories.
-
Clear the acceptance item. The executive coordinated plant technicians to resolve the software calibration within seven days, securing formal customer acceptance and releasing billing.
-
Settle the freight dispute. Simultaneously, the interim leader brought the German key account director and the customer procurement head together. They agreed the freight charge reconciliation against the master agreement and secured payment within ten business days.
-
Record the result. One page per open item went to the Group CFO and the plant managing director.
The subsidiary received its required liquidity from its own unbilled work and resolved receivables, not from another group loan. For nine months, nobody held one view of subsidiary cash flow across the ledger, factory floor and customer file. What changed was visibility. The Group CFO could now see which part of each request was structural, external timing or avoidable.
Frequently Asked Questions About Subsidiary Cash Flow Management
Does a Funding Request Indicate Subsidiary Underperformance?
No. A funding request shows only that cash going out exceeds cash coming in. Growth, seasonal stock build and customer payment terms can each push subsidiary cash flow negative without management failure. A recurring request with no operating explanation is different. It usually points to a gap between functions, such as a delivered order that nobody can bill. Treat it as an open question and ask for the explanation with the transfer.
Should Headquarters Require a Recovery Plan Before Fulfilling Essential Obligations?
No. Payroll, critical suppliers and statutory payments cannot wait for a recovery plan, and a plan needs time to test. Withholding them from a manufacturing subsidiary can stop customer deliveries and leave local managers without a workable option. Funded obligations also give the recovery room to work, because payroll and supply stay secure while teams clear the causes. Agree the operating actions in parallel, each with an owner, a date and a review.
What Documentation Should Accompany the 13-Week Cash Forecast?
A forecast models timing from the current ledger. It cannot show cause. Ask for three further items. First, a list of completed work awaiting customer acceptance. Second, an ageing register of disputed invoices with the stated cause of each dispute. Third, a payment schedule that names the suppliers. Ask the plant to name one owner for each item. Together they show whether each part of the request is structural, external timing or avoidable.
When Should an Organization Deploy Interim Finance Leadership?
Use a two-question test. Can the existing team secure decisions across sales, operations and headquarters? Does a named owner have the time to lead the work? If both answers are yes, keep the work internal and sponsor it at Group CFO level. If either answer is no, the gap is authority or time. The work then needs a defined mandate for an Interim CFO, with the terms set before the first day.
Conocimientos relacionados y siguiente paso
An unexplained funding request repeats the same decision every quarter. Group can fund the plant and fix the cause together.
Lecturas relacionadas:
-
Dificultades de los proveedores en Europa: qué hay que comprobar mientras siguen llegando los envíos
When the cause spans sales, plant and finance, one owner rarely holds the authority to clear it.
CE Interim provides cross-border executive leadership for critical business transformations. A proven, mandate-matched executive can be ready to start within 72 hours of the completed mandate brief.
To restore one verified view of subsidiary cash flow, talk to a Socio interino de CE.
 EN
 DE
 FR
 IT
 PL
 RO
 CS
 SK
 HU
 ES
 RU
 AR
 SL