Na kratko
Invoice dispute resolution stalls when the facts sit at the plant, the exposure at group and the approval at the legal entity, and nobody holds all three. The issuing entity normally decides, within its delegation of authority. First, separate the disputed amount from the undisputed balance. Then record the evidence, compare the legitimate responses and name the approver. The file stays open until cleared funds arrive. Where a material backlog of such decisions lacks an owner, an Interim CFO can take it on.
Why Invoice Dispute Resolution Stalls in Practice
Consider a hypothetical dispute. A Western European group's Central European operating company invoices a third-country customer 850,000 Euros for a machinery batch. Ninety days later the invoice is still open. Procurement has sent a formal dispute letter citing technical delivery conditions, mismatched freight surcharges and missing assembly documentation.
The plant manager says the equipment met specification. The sales director fears that pressing for payment will damage a live contract renewal. Local finance has classified the whole invoice as disputed and stopped the reminders. The finance director cannot write the balance down without justification. At headquarters, the group CFO asks for a collection date that nobody can give.
Waiting and a verbal concession both protect the renewal, so both are understandable. Neither gives the customer an answer that the responsible directors have authorised. Meanwhile the evidence weakens, and the ledger may still show the balance as collectable. The contract's notice window, the renewal date and the next reporting date all keep running.
The useful question is not who is right but who decides, on what evidence, within which limits. A dispute passes the Board test when a contested balance threatens liquidity headroom at the next lender or reporting date. It passes too when it touches a live renewal.
Cross-Border Invoice Disputes and Decision Authority
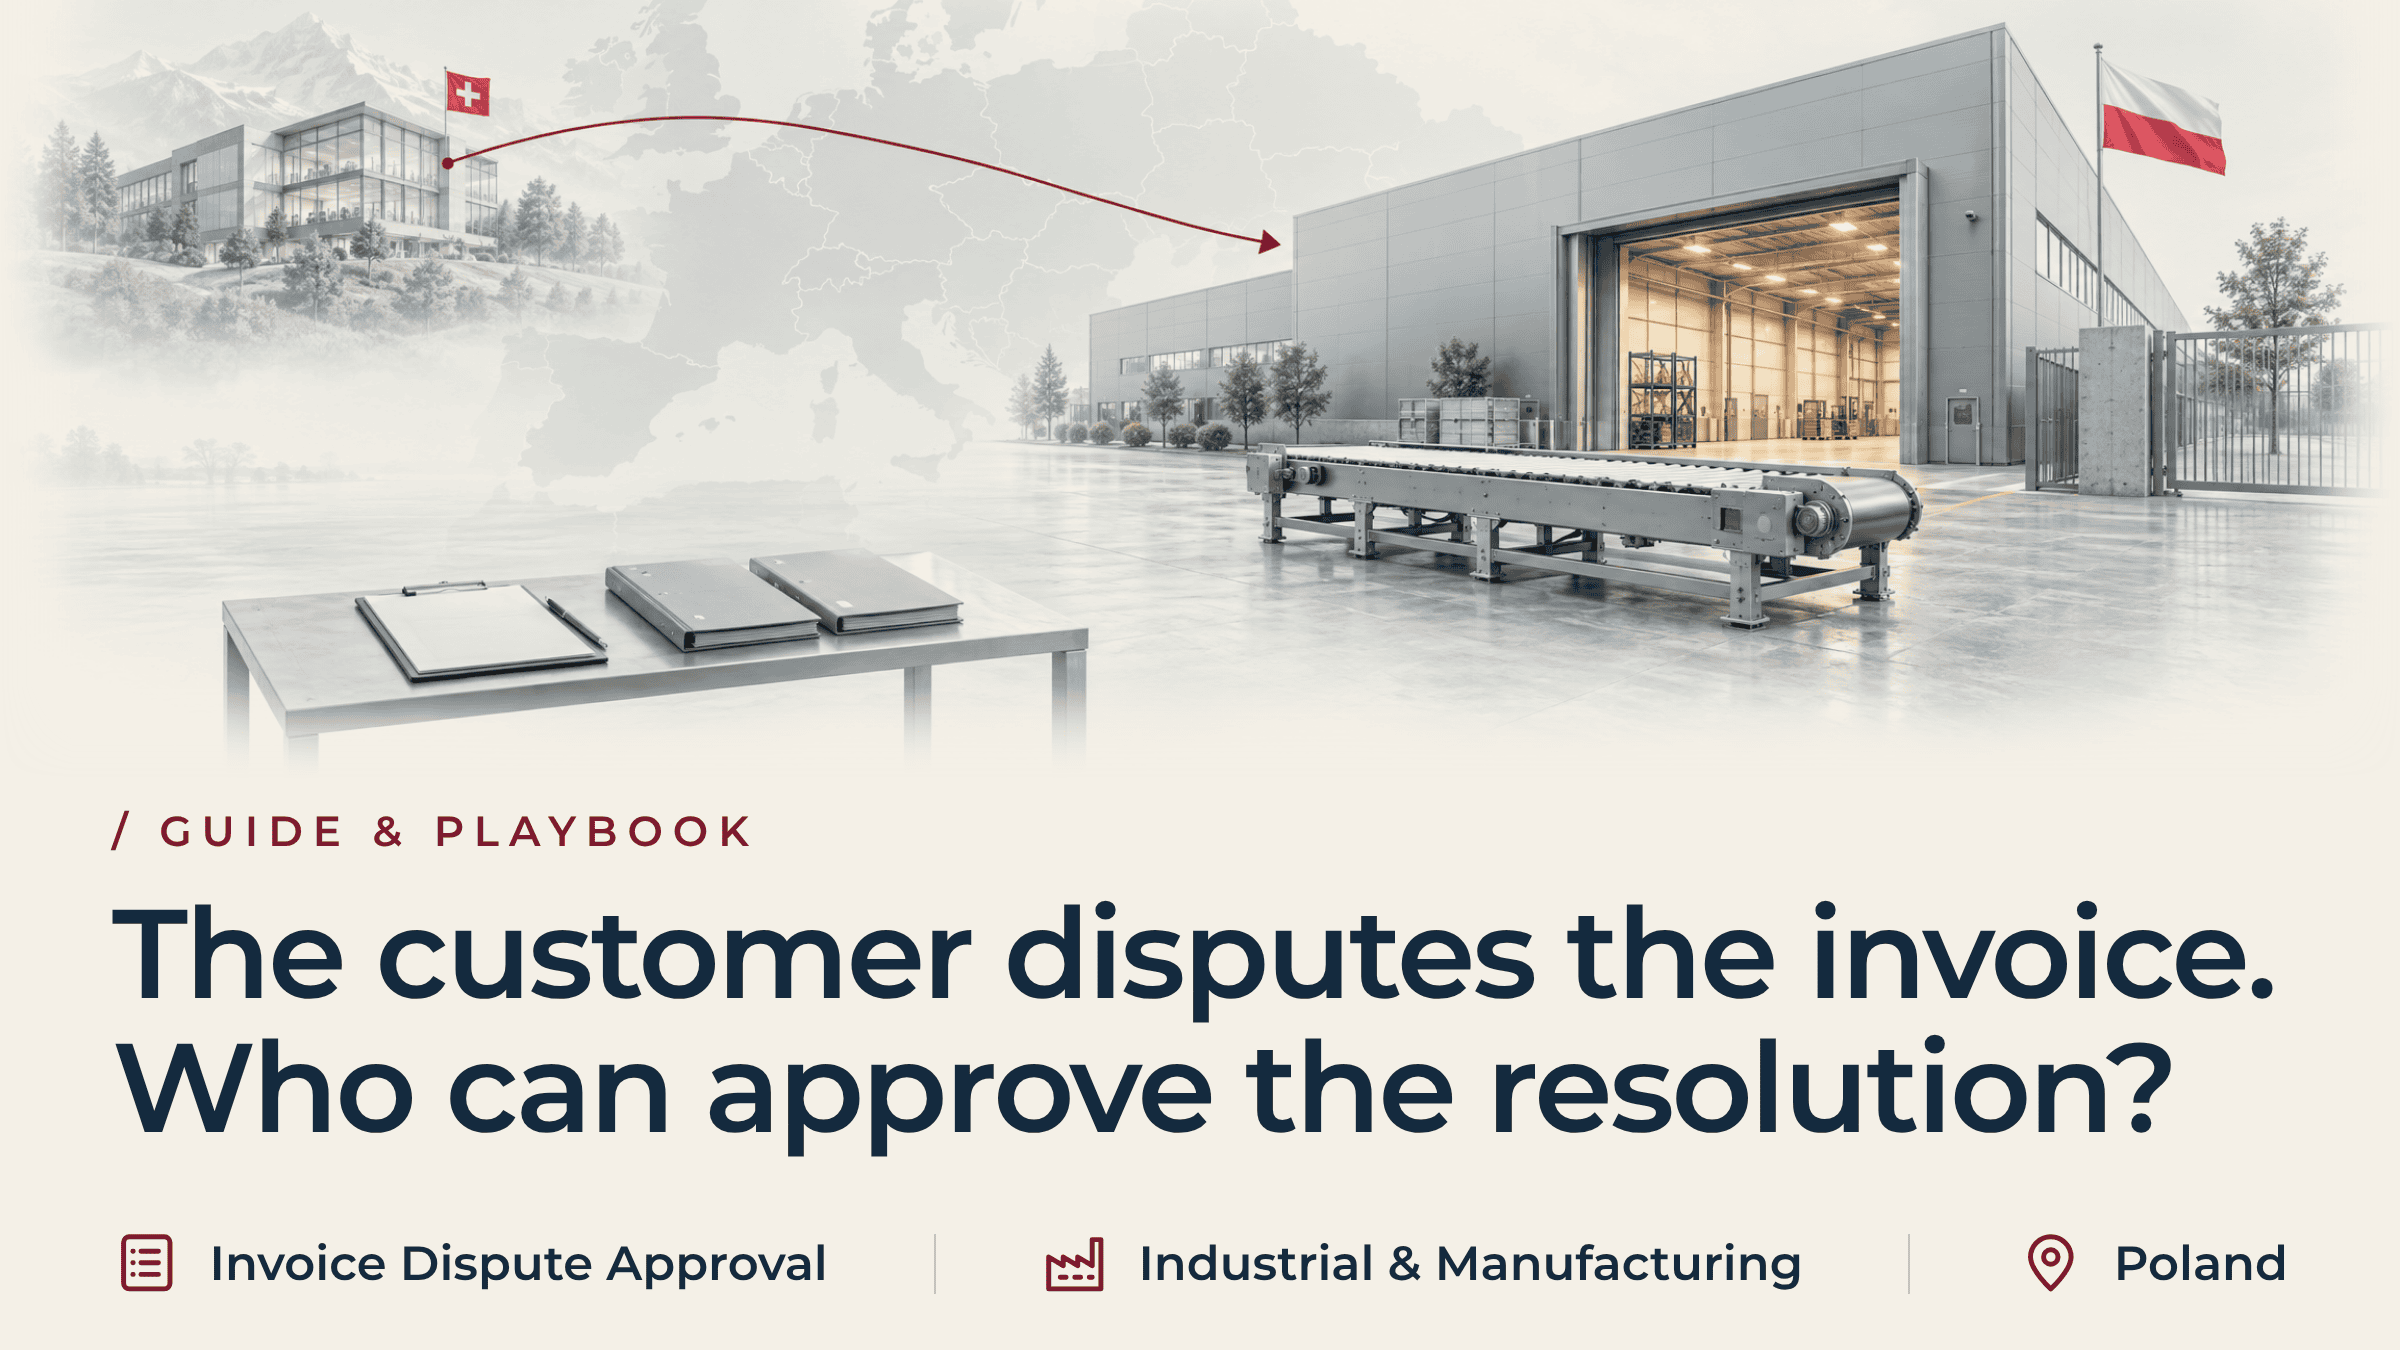
Take a Swiss or French group whose Polish operating company invoices a customer in a third country. The Polish entity is the legal creditor and holds the evidence at its plant. Headquarters holds the customer relationship. Neither can give the customer a final answer alone.
The Polish directors carry statutory responsibility for the entity's accounts and cash. Credit note and VAT treatment follow local rules. A concession agreed at group level therefore needs local approval. Headquarters needs control of precedent and cash. The local entity needs time to assemble the evidence.
Before any concession, the group checks the contract's law and forum. It also checks what the local directors need in writing before they sign. If group and local directors disagree, the group CFO and the entity's managing director decide first, then the Board.
Step-by-Step Process for Disputed Invoice Approval
An experienced finance executive, sitting or interim, works in this order. The issuing entity's directors approve, the group CFO or CEO is the mandate sponsor and the finance executive coordinates. Until the approver has signed, nobody offers the customer a concession or a payment date.
1. Isolate the Disputed Invoice Amount
The executive ring-fences each contested item, even where the customer withholds the whole invoice. In the hypothetical, the freight mismatch may be an administrative defect. The missing documentation may be an evidence gap, and the technical conditions a point to verify. For the undisputed balance, pressing early secures cash but can harden the renewal talks. Tying it to a release keeps negotiating strength but defers cash. The settlement value and root cause can stay open meanwhile.
2. Verify Customer Dispute Facts and Evidence
The executive distrusts two labels until the facts support them: local finance's "disputed" status and the plant's "met specification". Each is a position, not a fact. The team reconciles the contract, specification, proof of delivery and written objection. If the customer contests the facts, a joint or independent technical check outweighs either side's account.
The issuing entity also sends the customer a dated written holding response, cleared by its directors. It acknowledges the letter, names one contact and gives the date of the facts review. It carries no figure and no payment date.
3. Evaluate Credit Note and Settlement Options
An experienced executive weighs each option with its cost and usually concedes last, because a concession sets precedent.
-
Correct an administrative defect. Amend the invoice or issue a credit note if billing used the wrong price or tax rate.
-
Complete the remedial work. Fix verified technical snags by an agreed date.
-
Agree a documented concession. Grant a bounded adjustment for a written release and payment of the remainder.
-
Seek specialist review. Involve advisers where the evidence stays contested.
-
Maintain the invoice. Where verified evidence supports it, answer the claim in writing.
Each carries a trade-off. Remedial work costs plant time. A concession sets precedent. Specialist review slows the answer. Maintaining the invoice tests the renewal.
4. Determine Credit Note Approval Levels
Credit note approval normally sits with the issuing entity's directors, within the group's delegation-of-authority matrix. Above their limits, the group CFO, a commercial committee or the Board decides. An interim title does not by itself grant settlement authority.
5. Monitor Payment Following Dispute Approval
A credit note changes the ledger, not the bank balance. Approval, execution and receipt are three separate events. Management reporting keeps non-cash adjustments apart from cash, as IAS 7 excludes non-cash investing and financing transactions from the cash flow statement.
Until the dispute closes, the Board faces a trade-off. Carrying the balance as collectable protects the renewal but risks an overstated receivable at the next reporting date. Recognising the uncertainty early protects credibility but can signal weakness to the customer and lenders. The group also fixes two escalation points in advance: a date for the first decision, and the ageing limit that moves the file to the finance director, then the sponsor.
Components of an Invoice Dispute Resolution Approval Record
The approval record gives sales, finance and the plant one document to read. Open it before any settlement, write-off or credit note, and close it on cleared funds. It is a management aid, not a legal settlement form.
-
Invoice and claim: number, amount and issuing entity.
-
Disputed issue: contested lines, the customer's stated reason and the undisputed balance.
-
Evidence: delivery records and inspection logs, who verified each and any independent check.
-
Options and consequences: each response costed for margin, cash, precedent and reporting treatment.
-
Authorised choice: the approver's decision, with any dissent recorded.
-
Approver and limit: the named approver, checked against the delegation matrix, and the escalation date.
-
Customer response: holding response, signed agreement, release of claims and payment date.
-
Implementation owner: who issues the credit and follows the payment.
-
Confirmed receipt: treasury confirms cleared funds.
Role of an Interim CFO in Managing Disputed Invoices
Existing leaders may handle invoice dispute resolution on their own, and should try first. One late invoice does not justify an executive appointment. A material backlog of decisions without ownership does. One large dispute can create it when its evidence, proposal and approval have no owner.
Three tests show whether a backlog is material. First, the Board test, with a trigger the group CFO sets in advance as a share of headroom. Second, whether any dispute has passed its first decision date with no owner. Third, whether the natural owners have a conflict or lack capacity. When two of the three hold, consider an executive.
The executive bridges the two sides. Local evidence becomes a recommendation that headquarters can approve. Group limits become an approval that the local directors can sign. With no stake in the account, the executive can hold one position for both.
Na spletni strani Začasni finančni direktor or Finance Director takes a defined mandate over a named list of disputes. The executive reports to the sponsor, who sets the approval limit before work starts.
Scope of Authority Short of Final Settlement
The mandate carries no automatic power to settle. The sponsor gives the executive four things in writing.
-
Single named contact for the customer on each listed dispute.
-
Power to hold any verbal concession or payment date until the approver has signed.
-
The right to convene sales and plant and to commission a technical check within a set budget.
-
A direct line to the sponsor on any breach.
The executive answers for a costed recommendation by the first decision date, a reliable weekly view and follow-through to cash. The mandate ends when each dispute has a named owner and approver, or has closed on cleared cash.
A CE Interim Partner governs the assignment. The Partner agrees the mandate and limit with the sponsor and assesses the executive for cross-border commercial experience. The Partner then reviews the weekly view, escalates any breach and manages the handover.
Case Study: Cross-Border Invoice Dispute Approval
A Swiss industrial automation manufacturer operated a dedicated sub-assembly plant near Poznan, Poland. The Polish entity issued a final milestone invoice of 1.1 million Euros to a major German packaging conglomerate for a bespoke conveyor system.
Background and Root Cause of the Invoice Dispute
Sixty days after issue, the invoice was unpaid. The German customer's procurement department sent a formal notice citing excessive vibration and commissioning that finished three weeks late. The customer intended to deduct 400,000 Euros in liquidated damages and operational disruption costs.
The Polish plant manager blamed the customer's uneven concrete foundation and refused to attend meetings in Germany. The Swiss key account director refused to challenge the customer. The director feared that tension would derail negotiations on an upcoming 5 million Euro framework contract. The invoice aged past 120 days, and group treasury had to inject emergency working capital to sustain the Poznan payroll.
Implementation of the Dispute Approval Process
The Swiss Group CFO engaged an interim finance director to resolve the impasse. The interim leader instituted a disciplined three-step intervention.
First, an independent technical expert worked alongside the Polish plant engineer and customer site technicians to measure the vibration. The inspection attributed 70 per cent to the customer's foundation settling and 30 per cent to an uncalibrated drive motor supplied by Poznan.
Second, the interim executive drafted a formal resolution proposal. Poznan would recalibrate the motor on site at a direct cost of 18,000 Euros. The Swiss parent offered a documented, one-time goodwill adjustment of 60,000 Euros. In return, the customer's procurement board formally waived all liquidated damages claims.
Third, the interim executive obtained signed statutory approval from the Polish managing director and the Swiss CFO for the 60,000 Euro credit note. It depended on the customer wiring the remaining 1.04 million Euros within seven business days.
The engineering recalibration took three days. The customer executed the signed release, and 1.04 million Euros cleared into the Polish operating account eight days later.
Key Takeaways for Managing Disputed Receivables
The composite sets no benchmark, and the settlement was a commercial agreement, not a finding on legal entitlement. It was one invoice, but it carried a backlog of decisions. The evidence, the proposal and the approval each lacked an owner until the interim finance director supplied them.
The customer claimed 400,000 of the 1.1 million Euros. The other 700,000 Euros carried no stated objection but stayed unpaid until the release. The approvers linked the whole balance to it. That was a judgement, not a default.
Frequently Asked Questions About Invoice Dispute Approvals
Does a customer claim make the entire invoice balance unrecoverable?
No. An objection usually touches one component, such as a freight charge or a milestone, and does not establish the recoverable amount. Isolate the disputed portion and show the rest on its agreed date in the forecast.
Who has the authority to approve a credit note for a subsidiary?
The issuing entity's authorised directors, within the group's delegation-of-authority matrix. Headquarters sets the limits but cannot replace the local approval. Local company law and tax rules apply, so confirm with advisers.
Does issuing a credit note signify full dispute resolution?
No. A credit note reduces the receivable and brings in no cash. Record it as non-cash and link it to payment of the remainder. Treat the dispute as open until the agreed payment clears.
What criteria confirm that an invoice dispute is fully resolved?
Three facts must hold. The customer's authorised representatives have accepted the settlement in writing. The agreed work is complete. Cleared cash for the agreed balance sits in the bank. Record any shortfall as a new item with its own owner and date.
Povezano znanje in naslednji korak
A disputed invoice becomes cash only when a named approver, within a known limit, authorises the response and someone follows it to cleared funds. These pages cover approval limits, the finance role and the cash process.
Priporočena literatura:
When no one can authorise the answer, a disputed balance stays reported as collectable while the evidence weakens.
CE Interim can propose an already vetted, mandate-matched, NDA-bound executive, ready to start after the completed mandate brief.
When invoice dispute resolution cannot progress because the authorised response has no dedicated owner, discuss a defined finance-leadership mandate with a Začasni partner CE.
 EN
 DE
 FR
 IT
 PL
 RO
 CS
 SK
 HU
 ES
 RU
 AR
 SL